Overview
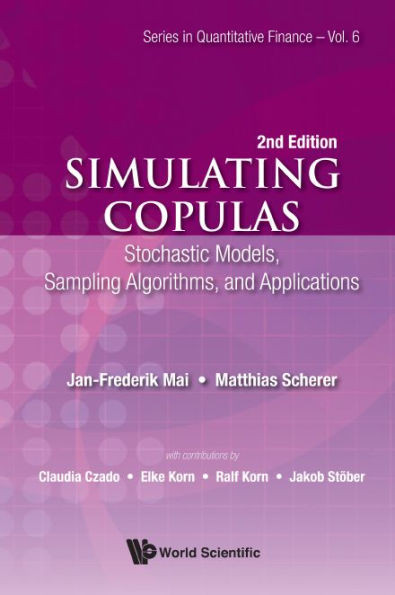
The book provides the background on simulating copulas and multivariate distributions in general. It unifies the scattered literature on the simulation of various families of copulas (elliptical, Archimedean, Marshall-Olkin type, etc.) as well as on different construction principles (factor models, pair-copula construction, etc.). The book is self-contained and unified in presentation and can be used as a textbook for graduate and advanced undergraduate students with a firm background in stochastics. Besides the theoretical foundation, ready-to-implement algorithms and many examples make the book a valuable tool for anyone who is applying the methodology.
- | Author: Jan-Frederik Mai, Matthias Scherer
- | Publisher: Quantitative Finance
- | Publication Date: Aug 02, 2017
- | Number of Pages: 356 pages
- | Language: English
- | Binding: Hardcover
- | ISBN-10: 9813149248
- | ISBN-13: 9789813149243